
The BIgger Picture
To access the full content of each article, subscribe to The Bigger Picture
Read the articles
A Risk Too Far
National resilience, distribution economics and the hidden costs of a 2034 television switch-off....
White Paper | AI: where we are now
This latest presentation is on some thoughts around AI and why it may pay to be sceptical even though firms are likely to use it as an excuse to drive through significant cost savings.
White Paper | China- the state of play and what it means for advertising
This latest presentation looks at the situation in China and the possible implications for global advertising spend.
White Paper | State of the UK Nation
This presentation focuses on the UK post-the General Election and gives an outline of the political situation as well as the economy and the advertising outlook.
White Paper | Consumer Package Goods
This presentation looks at the CPG industry, some of the medium to longer term trends that are likely to influence the space as well as the general market view on the CG names.
White Paper | European Broadcasters
The latest presentation is on the European Broadcasters, how they are perceived by the market, the mistakes they are making and how they can improve the situation.
White Paper | Key Sector Trends
This month mainly looks at the sector trends for six key verticals within the UK market. It focuses on less obvious trends occurring mainly over the medium to longer-term.
There is also a short UK macro overlook looking at where the economy currently stands and the position of the consumer
White Paper | The implications of 2024 revisited
An update of what I published last summer on the implications of what is happening in 2024 on the electoral front, and what it means for the Media and Tech sectors. Some of the points will be obvious but most will not. Most are based around advertising and Tech but not all.
Given the world faces an ‘interesting’ 2024, what happens globally will leave its imprint on the space
The Tech job cuts – a phase or a permanence?
Snap stated it would cut 10% from its workforce when it announced its results, eBay is reducing 9%, and Alphabet and Amazon have both announced cuts.
Some thoughts on why – from an analyst perspective – Tech companies are laying off staff even though results were better than expected, (and the answer is not as straightforward as you think).
What the US and European TV markets can learn from one another
One of the major issues impacting the SVOD streamers is that their general approach of seeing the world in the light of the US market has caused them strategic problems.
This is a short piece from Christy Tanner and myself taking a brief overview at what the European and US TV markets can learn from one another. This is a starting point for a much deeper conversation but good to get the ball rolling.
Annual White Paper Part 2 | The Year Ahead 2024
The second of three presentations for my annual review.
This annual piece is looking at what I see to be the main macro and Media and Tech trends for 2024 as well as what it means for individual sub-sectors.

Annual White Paper Part 1 | Where we are now
The first of three presentations for my annual review.
This presentation gives an overview of where things stand for 2023 both when it comes to the macro and sector trends. As with last year, it’s intended to be part of a series, including my outlook at 2024 and an update on the medium/ longer-term trends.
Thoughts on the Premier League deal
Some thoughts on the new Premier League deal – these are more general ones than the specific detail of the packages, which have been reported in detail elsewhere.
The value of X
There has been some excitement over the news that X (aka Twitter) has seen its valuation fall from the $44bn that Elon Musk paid for it to a reported $19bn with the view that Musk has driven the valuation of the firm into the ground. I wanted to put some context on things from an analyst standpoint and give my thoughts as to why things are more complicated (and more unlikely) than that.

Omnicom acquires digital commerce assets of Ascential
Some thoughts on the announced acquisition by Omnicom of the digital commerce assets of Ascential.
White Paper | How to make the case for marketing
An in-depth piece looking at what Boards think of marketing, the accounting standards, what those in marketing can do to persuade companies to either invest more or maintain their marketing spend, and some of the suggestions I would use to put this into practice.

Revisiting where we are with the Telegraph Media Group: some updated thoughts
Some updated thoughts on where we stand now with the sale of the Telegraph Media Group.
Quarterly White Paper | Quo Vadis: The lessons from the results season and what they mean moving forwards
The main findings from the Media and Tech results, the bigger picture macro findings, and conclusions.
Without stealing the thunder of the presentation, the season can be summed up by one word: reassuring.
Too much to bite: Why an Apple purchase of Disney is (probably) too much
Some thoughts on the prospects of Apple buying Disney.
In summary, I am sceptical for the reasons which I outline. However, I do think a minority stake holding may make more sense to both parties
White Paper | The UK Outlook
Some thoughts on where we are in the UK, where we go next and then what it likely means for the advertising environment.

A flood of results from Media and Tech companies
As we see a flood of results from Media and Tech companies I share key finds from the results.
In summary, after some concerns raised by comments from several of the agency groups, the results have generally been more positive, bar some of the comments from ITV.
Cashing in. Pensions, rising interest rates and the implications for UK Media and Tech
Sometimes the more boring topics can be the most important ones fundamentally, mainly because, while dry, they tend both to have a major impact on decision-makers’ actions and incentives and are important when it comes to areas such as rules-making (as the phrase goes: “People do not do what you expect, they do what you inspect”). This is the case when it comes to pensions, particularly for the UK market.
What does this mean for the UK Media and Tech sectors?
The Implications of 2024
Politically, 2024 is going to be a big year.
Here are some thoughts on why the Media and Tech sectors need to be thinking about this now and next year, and what will be the likely implications for the Media and Tech sectors. Some of the latter will be obvious but some certainly will not.
So who will buy the Daily Telegraph and for how much? Some thoughts
The Telegraph Media Group – which owns the Daily and Sunday Telegraph, and The Spectator magazine – is up for sale after receivers took control of the group. Some thoughts on who will buy the assets (and will not), how much they will pay and what it will mean.

A breakthrough at last? Apple’s new headset product- some thoughts
The FT has billed them as its most important product in 13 years, but is Apple’s new headset really a breakthrough at last? I share some of my thoughts.

What CNN’s Town Hall with Donald Trump may tell us about media’s view of future growth priorities
CNN’s interview with ex-US President Donald Trump created a lot of heat and debate but I think the more interesting questions lie around what it may say about many media companies’ changing views of how they perceive future growth.

Ad Hoc | Pearsona non grata? Reflections on the Pearson AI conference call
Education and skills company Pearson held a conference call on the potential impact of AI on its business. I share some thoughts on what it meant
Ad Hoc | Sky’s deal for the EFL football rights – what it means and why it matters
Last week, Sky signed a new five-year deal starting from the 2024-5 season with the English Football League (EFL) which has some major implications.I share some thoughts on the rationale and what it may mean
Ad Hoc | $50bn or $144bn? YouTube’s valuation and why it is unlikely to be valued as much as Netflix
There has been some speculation that Alphabet will spin off YouTube into a separately listed company to unlock value, with some suggestions that YouTube may be as valuable a property as Netflix. I have my doubts on such a plan, but I wanted to outline why a YouTube valuation is unlikely to reach anywhere near that of Netflix.
White Paper | Steady as it goes: The outlook for the upcoming Q1 results season
The Q1 results season is just about to start so I share my thoughts of what are likely to be the key points on both the macro / advertiser side and also for the Media and Tech sectors.
In summary, I don’t think there will be much change in the messaging from companies although Tech is likely to be boosted not so much by good results but by a changing view on the interest rate environment and a re-emphasis on efficiency.
Annual White Paper Part 3 | Where we will go
This is the third and final part of my Annual Review, which looks at the medium to longer term trends I expect to see in the Media and Tech space.
As usual, I will give a macro overview first, and really for the same reason as always – that to understand what is likely to happen in the Media and Tech space, it is critical to understand the wider trends. That has been proven especially to be the case in 2022 with rising interest rates wreaking havoc on the Tech sector and it will continue to be the key determinant moving forwards.
Annual White Paper Part 2 | The outlook for 2023: Time for the bright side
This is the second of a series of three notes looking at the key trends in both the Media and Tech sectors and also the wider macroeconomic side that influences their development.
The first one published last month dealt with where things stood on both the wider microeconomic side and the Media and Tech space. This second piece is about what I see as the trends in 2023 – both macro and Media / Tech sector wise., with the third one to follow about the medium to longer-term trends to think about and what they mean.

Annual White Paper Part 1 | Where we are now
Where we stand in Media and Tech, and the broader macro picture.
The first in a series of three presentations looking at the Media and Tech landscapes. I will not spoil the content but, in essence, I think for many of the sub-sectors involved within Media and Tech, we are now at a turning point when it comes to their future development. I will explore that in more detail in the future releases but, for now, I thought it was very useful to start with a recap of where we stand today.
White Paper | The Tightening Noose: A deep dive into the Q3 results for the established social media networks
The Q3 results season has been mixed across the board, in terms of both results and the messages given about the wider macroeconomic landscape. Certainly, the results from several sectors, such as Airlines, Luxury Goods, Financial Services and most (if not all) of the Consumer Goods space, suggest an environment where demand is holding up and price increases are tolerated more than expected, although there are plenty of other examples to suggest the pain is increasing. Yet when it comes to the social media space, the message seems to be one of gloom, at least for the short term. There may be reasons for thinking that gloom may be more prolonged.
This deep dive into the social media networks raises a number of points, some of which may be obvious, others not.

Ad Hoc | How do TV networks capitalise on the digital stumble?
Over the past six months, there has been a noticeable step-up in the level of investment into the media measurement industry, particularly from the private equity space. The $16bn purchase of Nielsen, together with the $325m investment by Goldman Sachs into TV measurement business iSpot, has highlighted the growing interest in the space.
I have joined forces with The Attention Council CEO Andy Brown to write a White Paper arguing for three key requirements for advertisers to evaluate TV alongside digital video.
White Paper | A game of two halves: Where we stand in the SVOD wars
Back in late February, I wrote in my then quarterly piece “The streaming endgame: what History teaches us about the likely finale of the battle for streaming dominance”, that the paid Subscription Video on Demand streaming model was in long-term danger and probably unsustainable longer-term.
The timing of the paper was certainly fortuitous. Two months later, at its Q1 results, Netflix reported a subscriber loss for the first loss and gave guidance on Q2 subscriber losses of 2 million that shocked the market.
But where do we stand now? I thought it was a good time to revisit the SVOD landscape given all the events of the past seven months.

Ad Hoc | The collapse of the TF1-M6 merger
Groupe TF1 and M6 announced they were abandoning their planned merger.
Some thoughts on what it means, the implications and what is likely to happen next.
Ad Hoc | Some thoughts on the Disney fiscal Q3 2022 results
Disney published its latest set of quarterly numbers and there was a lot to digest. Here are my detailed insights and thoughts post-reading the results and transcript.
There were two general observations to make. The first is that the results were significantly ahead of analyst expectations at all levels, really driven by the Parks division on the financial side but also when it came to the streaming numbers.
The second observation is that Disney is still a company where the newsflow, share price and (more importantly) the management focus is still very much on the streaming side.
Quarterly White Paper | Wherein lies the future: Some thoughts on where the economy goes and what that means for the Media space
I was going to focus on the Food Delivery space this month, but the incoming requests I have been getting have been overwhelmingly weighted towards the macroeconomic side of things and what are the likely next steps. So, I am going to focus on that (apologies to those who wanted a review of the Food Delivery space – it is coming). This will also be a Quarterly piece. Although it is a bit earlier than the timetable suggests, the topic demands an in-depth look.
I will focus on three parts. First, what I think will happen in the short term. Second, the outlook for the next 12-18 months. Third, a short summary of what it means for the Media and Tech names. Hopefully, by the end, you will have some food for thought and ideas on what it means for the space.
Ad Hoc | Flash thoughts -What now happens with Microsoft and Netflix?
For the past several months, I have been suggesting that Microsoft may be an eventual buyer of Netflix.
Following the advertising deal announced between the two companies I share some insights.
White Paper | The Devil’s Advocate: Six arguments as to why much of the digital advertising spending may be wasted
Much has been made of the efficiency of digital advertising and how it leads to better outcomes.
To be upfront, I am a sceptic and I thought for this monthly piece that it would be good to present a case for the prosecution as to its value. I have focused specifically on online-centric platforms, as opposed to the offshoots of traditional media e.g. AVOD for Broadcasters, the latter of which I believe has a central role to play.
The aim of this piece is to pull readers away from the intricacies and to think about the bigger picture.
Ad Hoc | Over Here, Over Paid and Over Sold – why the SVOD giants have misjudged the European opportunity
Whilst the whole SVOD streaming war opportunity is global, all the major players in the market are American – Netflix, Disney+, Comcast, Discovery etc. Less well known, but just as important, is that the same goes for the majority of the analysts and investors who cover and own these names. These are the ones who ultimately judge – from a share price perspective at least – the success of the streaming giants’ plans. There are exceptions of course (me for example) but we are in a minority. Moreover, being brutally honest, it will always be the American perspective that will determine how people see the potential opportunity and how companies make their decision.
Quarterly White Paper | The eye of the storm: 12 reflections on the latest quarterly results
At the end of the calendar first quarter results season, it is fair to say that there is a lot for companies to navigate at the moment: inflation, the lingering effects of Covid particularly in China, the war in Ukraine and so forth. I have gathered the key messages to come out of the reporting season and they may not be the most obvious ones, there are also a number of other trends that I could have written about (e.g. the performance of the Tech companies), but these are probably the most interesting ones.

Ad Hoc | Plus ça change for the European Broadcasters
Looking at the European Free to Air Broadcasting space over the past 20 years seems like a classic case of the French phrase “the more things change, the more they stay the same”.
Linear TV audiences have declined, and new technologies have taken away both younger audiences and advertising money, while the rise of streaming services have changed fundamentally the way consumers watch video content.
On the other hand, the major players in the European Broadcasting space, at least in the major markets, remain the same.
White Paper | Republicans buy sneakers revisited: why advertisers should be aware of the growing political risks
With the collapse of the Netflix share price following its shocking Q1 results, and the news of Elon Musk’s accepted bid for Twitter, the other major story in the US Media and Tech space over the past few weeks has been Disney’s increasingly bitter dispute with Florida’s Republican Governor. What does this mean to advertisers and agencies, and why do they still need to be aware of the growing anti-sentiment amongst conservative voters?
Ad Hoc | Pushing through the pressure: a quick guide as what to expect from the upcoming Q1 results season
This week marks the start of the results earnings season from calendar Q1, barely weeks after the Full Year results season ended. Ahead of the reporting season, here are some thoughts on the main topics I expect to come out. When I have written these before, I have usually focused on what I expect for the Media and Tech areas and, while the bulk of this piece will be focused on that, this time I thought it would be worthwhile to throw in some thoughts on the overall direction for companies across the board, as this will provide a better context to the commentary on the Media and Tech side.
To consume or not to consume? What is likely to happen to – and with – the consumer market over the short to medium-term
The world seems to be suffering from the Chinese curse of “may you live in interesting times”. The geopolitical situation remains febrile and the economic front concerning. Explored in this piece is the trends that are impacting (and likely to impact) the consumer; (2) where the consumer is now and (3) some thoughts and conclusions as to what is likely to happen next and what it means for the sector.
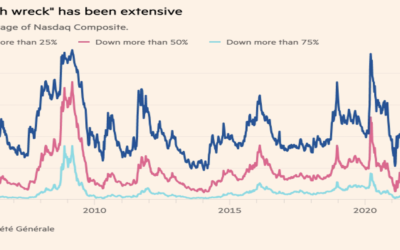
Ad Hoc | Discounting the Future: why rising interest rate expectations are exacerbating the fall in Tech stock names
The markets have had a choppy start to 2022, given the combination of concerns over inflation, rising interest rates and, in recent weeks, the terrible events in the Ukraine and the after-shock effects. However, the Tech sector has been badly hit. Chinese stocks, in particular Tech names, also look to be heading for the worst weekly performance in a year, with the recent Covid outbreaks and imposed restrictions impacting the markets.
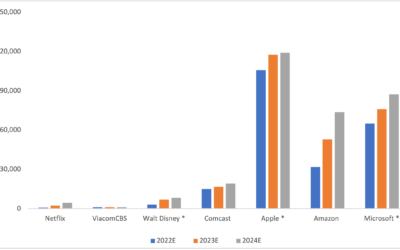
Quarterly | The Streaming endgame: what History teaches us about the likely finale of the battle for Streaming dominance
As far as the markets are concerned, there are growing doubts over whether the paid streaming subscription model will ever provide the returns needed to justify their valuations. I think that scepticism is right. In fact, I would go further and argue that the paid streaming model is in long-term danger.
The muddying waters – key thoughts on the upcoming Q4 results season
This upcoming week will perhaps be the single most important week for company results in the reporting season, at least for US companies – around half of the Dow Jones Industrial Average and c. a quarter of the S&P 500 are expected to report this week.
As usual, I will share some thoughts as to what I think will be the main messages from the reporting cycle, mainly for the Media and Tech businesses but some wider macro-economic themes as well. Also, as usual, I will try and avoid the obvious points and highlight perhaps some of the areas that maybe get less attention.

Ad Hoc | Why we should get rid of Zero-Based Predicting
Every year, usually in January (but sometimes in December), we have the annual round of predictions for the upcoming year. It is a seasonal tradition, much discussed and talked about, and in some cases loved. However, it is also a tradition that risks guiding companies towards the wrong decisions, and forecasters to miss light of the bigger trends.
Ad Hoc | The rush for music catalogue rights
One of the hottest areas for rights acquisitions in 2021 and continuing into 2022 has been the purchase of the music catalogues of artists (Warner Music Group buying David Bowie’s catalogue for an estimated $250m+ last week). It is one that has attracted a range of buyers, from the established music giants such as Universal Music Group (eg Bob Dylan’s catalogue for c. $350m), Sony Music (e.g. Bruce Springsteen for an estimated c. $550m) and Warner, private equity firms such as KKR or specialist groups such as Hipgnosis (e.g. 50% of Neil Young’s catalogue for $150m) – and sometimes a combination of the players, such as BMG and KKR. I have laid out some quick thoughts below as to why, and also whether this will continue.

Ad Hoc | Will Cannes be Canned?
My only occasion of going to the Cannes Lions festival was in 2019. That was a good year for the show: the weather was glorious, the conference had none of the worries about Covid that were soon to engulf the world and, more to the point, Cannes Lions generated double digit organic revenue growth, bouncing back after what had been a slightly rocky period. However, things have changed since then and the cancellation of the physical event (if not digital) for two years running raises questions over its future direction. My view is that there is a high possibility / probability that the Cannes Lions physical event does not return or, if it does, it may permanently be changed in nature. This is a view I hope is not right but it is worth exploring.
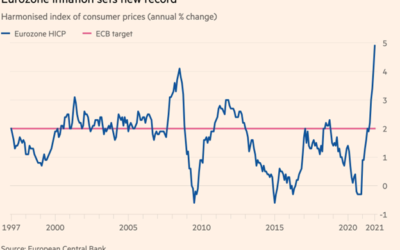
Ad Hoc | Are we about to see the return of high interest rates? Probably not
Some thoughts regarding the more hawkish tone on interest rates being taken by Central Banks, what it might mean for the Media and Tech spaces in general and why I do not expect this to lead to a return to significantly higher interest rates.
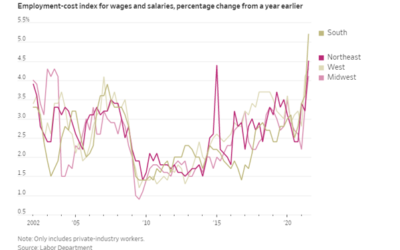
The seven thoughts-a-swimming – what the end of the year tells us about the sector
Christmas has taken on a weird feel this year. The news of the Omicrom variant has dampened hopes of a relatively quick return to normality and, while business would normally have wound down by now, it seems as frenetic as ever with no slowdown. There are several themes emerging at the end of the year, which are likely to feed into 2022 and beyond. Some may not be obvious, some you may disagree with but I would keep an eye on the following trends over the next 12 months.

Ad Hoc – The Coming Storm: Why the markets may be underestimating the political impact to (M)MAGA
President Biden’s falling ratings and recent Republican successes in state races point to an increasing likelihood of a Republican takeover of Congress in the November 2022 mid-terms. Here I examine what this would mean for the major Tech companies and who would be most (and least) at risk.
PI World Media Tech Overview Interview – November 2021
I sat down recently with Tamzin Freeman of PI World to discuss the Media and Tech sectors, and what is likely to happen for some of the key names including Facebook, Pearson TheTradeDesk, WPP and others. Watch the video here.
MediaTel’s Future of Media Conference 2021 – my Headline Speech
Watch my headline speech and view the slides from MediaTel’s recent Future of Media Conference.

Ad Hoc – Facebook Q3 2021 Results: The Key Takeaways
An example of an ad-hoc article that is normally only available to subscribers of The Bigger Picture.
Facebook 3 2021 Results – Key Takeaways
FB’s results were, like Snap’s, mixed. Q3 revenues of $29.01bn were below S&P consensus of $29.5bn (as were advertising revenues – $28.27bn vs $29.02bn) while Monthly Active Users (MAUs) were also…
Ad Hoc – Snap Q3 2021 Results: The Key Takeaways
An example of an ad-hoc article that is normally only available to subscribers of The Bigger Picture.
Snap 3 2021 Results – Key Takeaways
Snap’s shares fell nearly 27% on Friday post-the publication of their Q3 results on Thursday. Here are some thoughts on the numbers and the implications for the stock (and other names such as Twitter and Facebook).
Ad Hoc – Netflix Q3 2021 Results: the key takeaways
An example of an ad-hoc article that is normally only available to subscribers of The Bigger Picture.
Netflix 3 2021 Results – Key Takeaways
Generally, the results beat expectations. Q3 net subscriber additions were 4.4 million vs guidance of 3.5 million and consensus estimates of 3.84m (according to Refinitiv). Revenues were in line with consensus estimates at $7.48 billion but…

Bonus Article – The Roaring Twenties: Why advertising is likely to see a golden age
The Roaring Twenties: Why advertising is likely to see a golden age.
As an analyst, there is always a temptation to play safe and not be too far from the consensual view for fear of being wrong and lacking the appropriate cover. However, looking at the various trend factors, it is hard to escape the conclusion that the advertising environment is going to be strong for years to come…
Monthly – Republicans buy sneakers too: the increasing political minefield for advertisers
An example of an ad-hoc article that is normally only available to subscribers of The Bigger Picture.
I was planning to write a bit more about the Deliveroo IPO episode but my eye was caught by an opinion piece in the Wall Street Journal, entitled “What I Wouldn’t Give for a Shave That Isn’t Woke” (Link). The direct catalyst was the author’s annoyance…
Monthly – The coming pain: Why 2022 may define FAAMG (and the rest)
An example of an ad-hoc article that is normally only available to subscribers of The Bigger Picture.
One of the topics I am particularly interested in is politics and the implications for business. It is an area that generally does not get that much attention but one that will very much be of fundamental importance for Big Tech (again, I am using shorthand for Facebook, Amazon, Apple, Microsoft and Google)…

Quarterly – Seven Reflections on a bloodied quarter
An example of an ad-hoc article that is normally only available to subscribers of The Bigger Picture.
Needless to say, companies’ results’ season was dominated by one topic and what the impact of the crisis will have on businesses around the world. Much remains uncertain including…